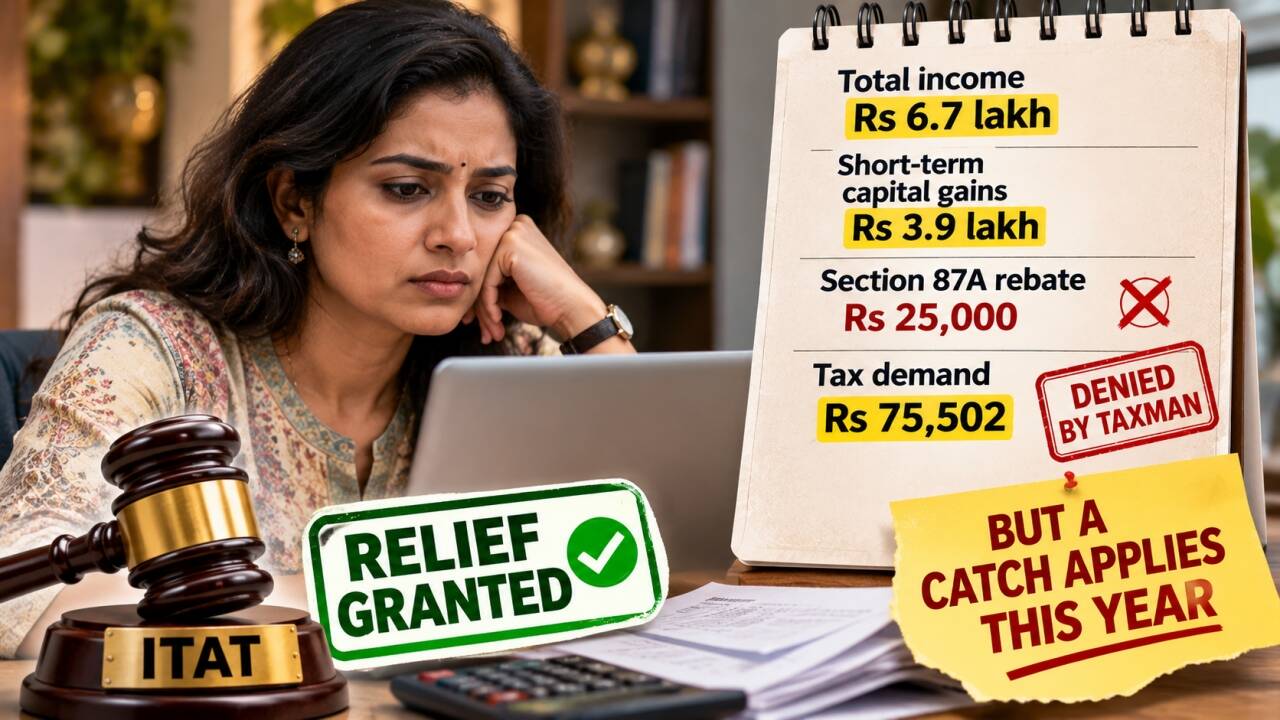
Income Tax Appellate Tribunal rules in favour of taxpayer over Section 87A rebate
The Hyderabad bench of the Income Tax Appellate Tribunal has ruled in favour of a taxpayer, holding that Section 87A does not expressly bar tax rebates when income includes short-term capital gains taxable at special rates under Section 111A. The tribunal observed that the law does not restrict the rebate if income is under the prescribed threshold. However, tax experts note that the Finance Act 2025 has expressly restricted the Section 87A rebate from this year onward.
By News Desk • 11/21/2026
Read FullThis page is a shareable card. Download our app to get the full swipe experience!